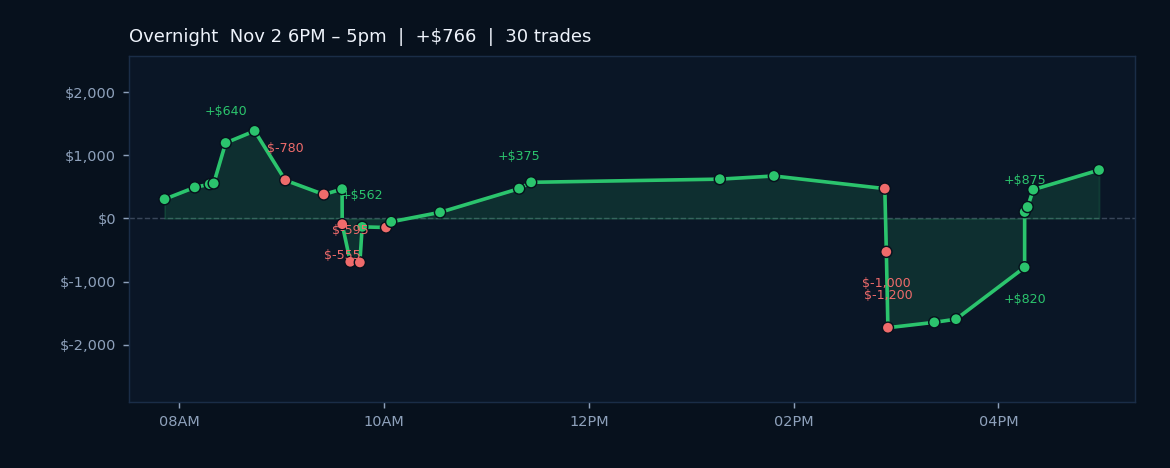
The session produced a steady +$766.50 gain (+0.41% day-over-day) against cumulative equity of $188,348.94, with the algo suite maintaining discipline across 30 trades and a 70.0% win rate (21 winners, 9 losers). Gross profit landed at $5,341.50 while gross loss totaled $4,575.00, yielding a 1.17 profit factor and average winner of $254.36 against an average loser of $508.33. The regime filter remains locked in low_vol mode at 100% confidence, which continues to favor tighter entry buckets and reduced slippage on smaller timeframe scalps. ES held above the overnight low of 7546 and stayed confined within the prior-day range (7570.75 to 7693.75), while NQ traded in a similar compressed band between 28038.2 and 28426.5 overnight, creating the kind of range-bound environment where mechanical risk management outperforms discretion.
The tape reflected post-election positioning with futures slightly constructive overnight: ES +0.2% and NQ +0.4% on the boards, buoyed partly by AMD's 8% after-hours move on the heels of solid guidance and Meta's $15 billion senior notes offering. However, trading volume and volatility remained subdued, consistent with the low-vol regime read. AI Pi at 51.9% and sentiment at neutral kept the model from deploying aggressive long bias, instead adhering to the win-loss distribution observed in the AI Recommendations: daily loss limits near $1,715 and $1,230 on the primary sim accounts remain in force, while the system continues to block consistently weak entry buckets including 08:30, 13:00, 10:10, and 15:30 UTC windows.
Looking ahead, AMD earnings fire after today's close and QCOM reports Wednesday, setting up a potential vol expansion into the balance of the week. Historical seasonality for midterm-year trading post-November 2 shows a mixed picture: the next week has averaged -0.49% with a 47% win rate across 19 years (1950-2026), a slight headwind versus the all-history baseline of +0.18%. The low-vol regime's high confidence reading may begin to crack if earnings catalysts push index futures beyond their overnight ranges, but until then, the algos are calibrated to exploit tight stops and elevated win rates in compressed price action.