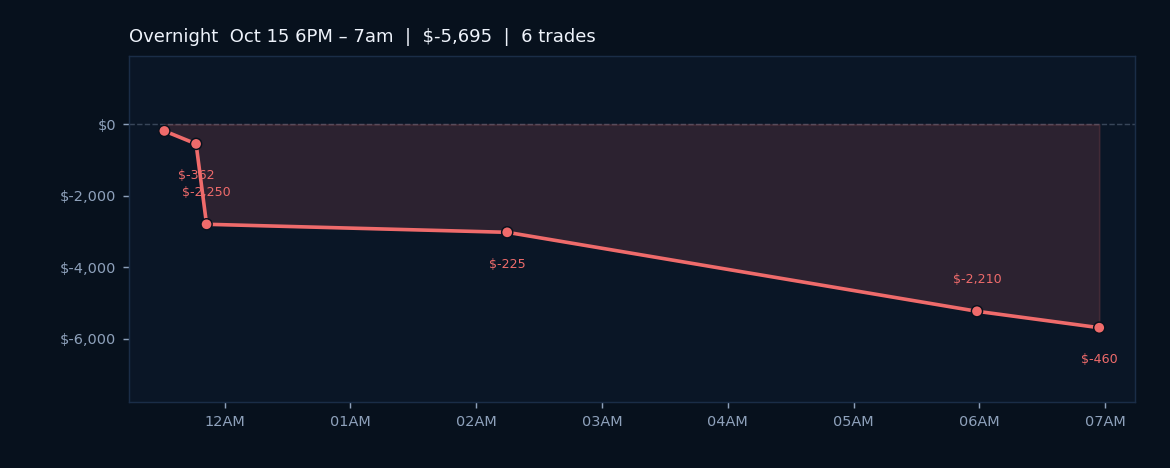
Overnight trading delivered a sobering $5,305 loss across 12 ES, MES, MNQ, and NQ contracts with a 25.0% win rate, setting a cautious tone ahead of today's cash open. China's State Council has stepped up rhetoric around AI innovation and risk evaluation while simultaneously tightening regulation in the platform economy, signaling mixed growth signals for the technology sector. Meanwhile, a tanker fire near the Strait of Hormuz and ongoing Russian diesel export complications add geopolitical friction to energy markets, though no immediate spillover pressure has materialized in equity futures.
Italy's trade data came in significantly weaker than prior readings, with the overall balance printing 1.773B versus the prior 8.240B, while EU-specific trade swung to a 0.327B deficit from a 1.251B surplus last month. This European softness enters a window where U.S. macro data remains quiet through the weekend, leaving sentiment vulnerable to any fresh headlines from China or energy markets. Tech earnings remain on the horizon with NFLX, META, and TSLA reporting next week, concentrating attention on valuations amid the mixed AI policy backdrop.
The AI Sentiment reading sits negative at 60.2% Pi confidence, and the regime filter registers chop with 100.0% confidence, signaling choppy, range-bound price action with no directional conviction. Seasonality data shows midterm-year Octobers typically deliver +1.08% gains over the following week with a 74% win rate, a historically green tailwind that conflicts with today's sideways technical setup. We carry five open positions (three MES longs, one ES short, one NQ short) with minor unrealized losses totaling under $425; all positions trade fixed RSI and ATM stop/target logic with no discretionary news overlay.