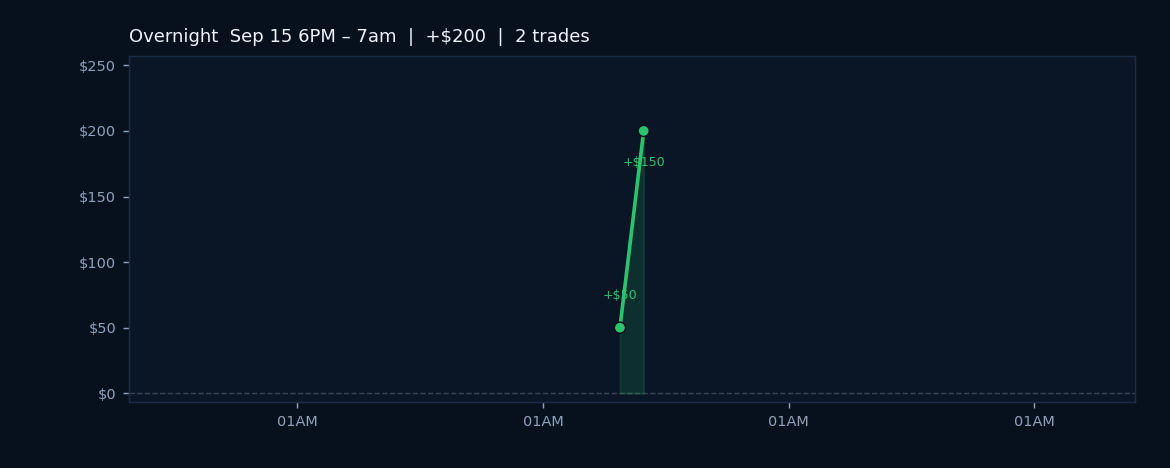
The overnight session delivered clean execution across ES and MNQ contracts, logging $241.50 in net profit with a 100.0% win rate on three trades, setting a constructive tone as markets prepare for the day's dominant event: the Federal Reserve's rate decision and economic projections. The central macro story shifts into sharp focus this morning as the Fed is expected to hold or adjust the Federal Funds Rate from its current 3.75% level, with FOMC communications and Chair Powell's press conference likely to dictate intraday volatility across both index futures and rate-sensitive equities. Overnight data showed US MBA mortgage applications fell 4.1% while the 30-year mortgage rate climbed to 6.97%, signaling cooling demand in rate-sensitive housing markets and reinforcing the inflation-backdrop against which the Fed will speak today.
Geopolitical risk softened marginally overnight as sources confirmed the Houthis told the US they remain committed to a 2025 ceasefire following weekend talks in Oman, reducing acute Red Sea shipping concerns that have weighed on energy and logistics trades. On the earnings front, IBM secured a $1 billion Chips Act award from the U.S. Department of Commerce, validating semiconductor-adjacent strength in the tech sector, while UK PM Burnham signaled fiscal discipline ahead of the budget, noting inflation concerns despite economic resilience. The macro backdrop remains mixed: seasonality data for midterm-year markets from this point forward shows a historical tendency toward weakness, with the next trading week averaging -0.23% returns and a 42% win rate over 19 comparable years, presenting a headwind to bullish positioning.
Current net positioning stands at four open contracts across ES and MNQ, carrying a combined unrealized loss of $134, with the regime filter reading trend at 100.0% confidence and AI sentiment tilted negative at a 55.8% probability reading. The algos maintain their four ES and MES short and long positions plus one MNQ 09-26 long contract at 29097.25, executing fixed RSI and ATM stop/target templates independent of headline flow or Fed event timing. Today's execution environment will hinge on the size and tone of Fed guidance; volatility expansion is likely in the final hour before and immediately after Powell's remarks, creating both risk and opportunity for mean-reversion and breakout trades within the trend regime.