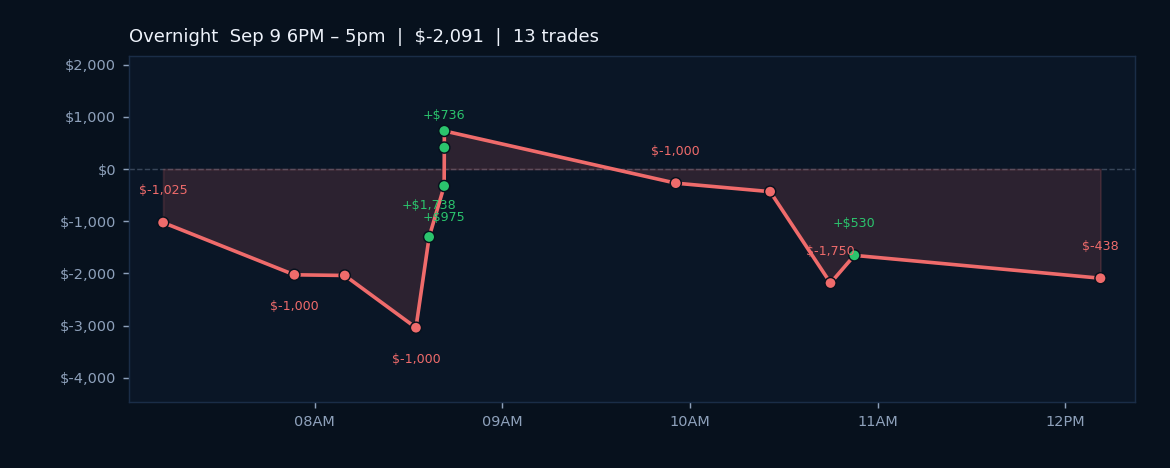
The session produced a net drawdown of $2,090.51, reducing cumulative P&L to $163,175.61 and marking a -1.26% day-over-day decline from prior session equity. Thirteen trades were executed across the contract suite, but the win rate collapsed to 38.5% with only five winners against eight losers. Gross profit of $4,297.49 was overwhelmed by gross losses of $6,388.00, resulting in a profit factor of 0.67 and average winners of $859.50 dwarfed by average losers of $798.50. The imbalance reflects execution challenges in a high_vol regime operating at full confidence, where whipsaw risk intensified across equities and energy as ES tested overnight lows near 7595, CL broke into triple-digit territory overnight (high 100.88) before retreating, and NQ struggled for directional conviction off the overnight low of 29043.2.
News flow tilted toward infrastructure tailwinds: Microsoft's announced expansion to 38 gigawatts of data center capacity by 2032, combined with a reported $5 billion Pentagon loan facility under discussion for FluidStack, underscored persistent AI capex momentum. Adobe reported Q3 earnings after the close, while OpenAI's pause of the $200 pro subscription plan signaled shifting monetization strategy. These developments sit against an AI Sentiment reading of negative and AI Pi holding at 57.2%, a middle-ground signal that offers limited directional tilt. Macro calendars loaded for Thursday morning: Core CPI m/m (forecast 0.2%), CPI m/m (forecast 0.4%), and year-over-year inflation prints will frame early-week risk appetite.
AI recommendations surfaced two structural constraints: enforced daily loss limits near $1,715 for the primary simulation and $1,230 for the edge variant, both well above today's actual loss but flagging concentration risk. Weak entry time buckets across 08:30, 13:00, 10:10 and others were flagged for blocking, suggesting time-of-day biases are now material enough to warrant structural filters. Seasonality for this midterm-year window shows a historical win rate of only 47% with average returns of -0.13% over the next trading week, a headwind that compounds an already negative sentiment backdrop and high volatility regime.
The combination of elevated regime volatility, negative AI sentiment, and mixed seasonality warns that mean-reversion and breakout patterns are likely to produce wider stop-outs through Thursday's CPI print and into the remainder of this week.