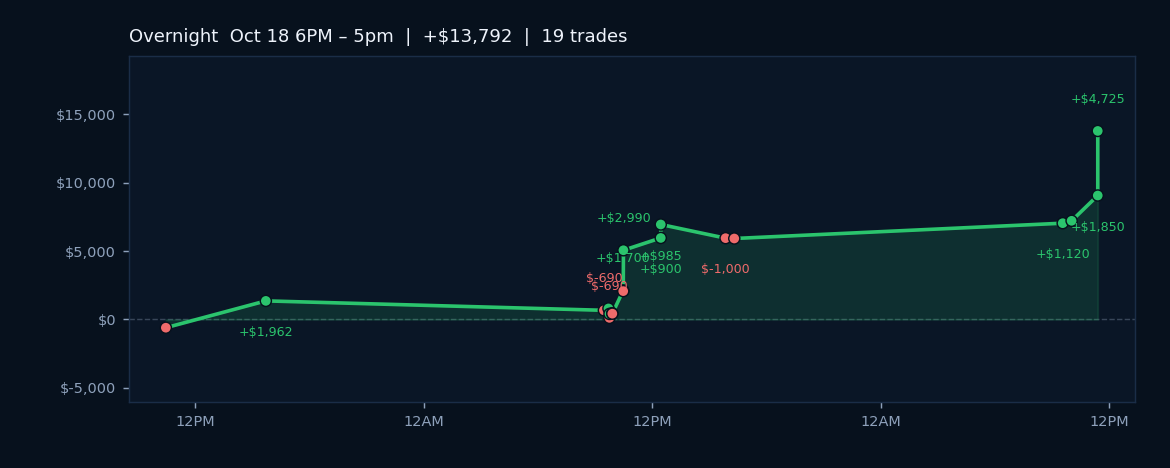
The week of October 19-23 closed with $13,792.50 net profit across 19 trades, posting a 63.2% win rate on just three trading days. The session delivered a profit factor of 5.46, with gross profit of $16,882.50 offset by gross losses of $3,090.00, bringing cumulative period total to $215,773.44. Thursday's session (October 22) proved the strongest entry point, capturing $7,870.00 in a single day, while Tuesday's (October 20) opened more cautiously with $1,357.50, suggesting the algos took time to calibrate entry positioning before the week's acceleration.
The high-volatility regime confirmation at 100% confidence created favorable conditions for mean-reversion and breakout tactics across ES and NQ contracts. With AI Pi holding steady at 70.6% and sentiment neutral, the environment favored technical execution over macro-driven positioning. Current AI recommendations emphasize discipline around entry timing and loss containment: the active loss-limit protocols suggest tightening daily drawdown thresholds (near $1,715 for primary accounts), while weak entry-bucket analysis continues to flag low-probability 5-minute windows (08:30, 13:00, 10:10) that warrant filtering on future sessions.
Looking ahead, the regime filter's high-volatility reading aligns with historical seasonality data showing +1.46% average returns for the S&P 500 in weeks following this point during midterm years, with an 84% win rate across 19 comparable periods. Major tech earnings (MSFT, GOOGL on October 28; AMZN on October 29) sit just outside the immediate forward window, but intraday momentum may reflect anticipatory sentiment shifts. The combination of sustained volatility signals and favorable seasonal positioning supports continued technical-driven execution, provided entry discipline remains tight around identified weak buckets.