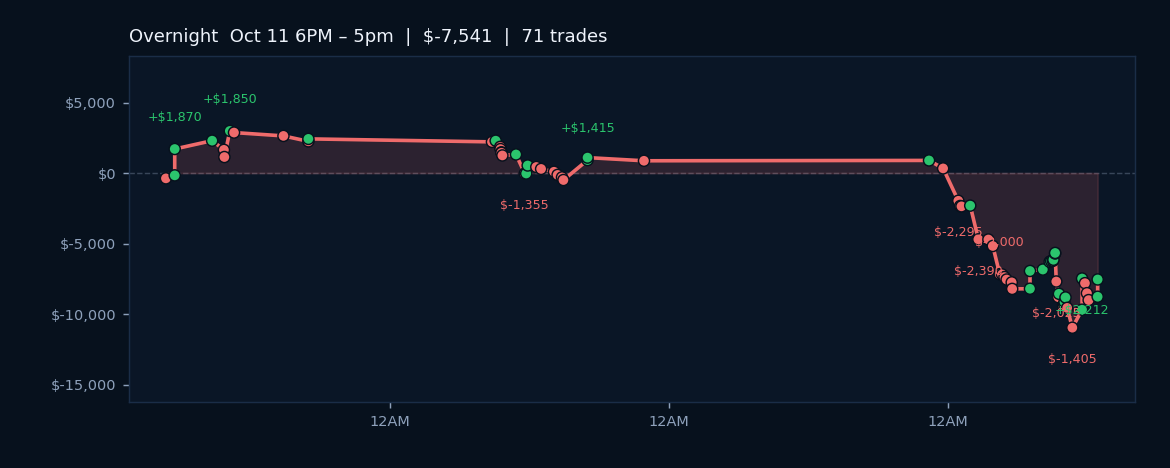
The week of October 12-16 delivered a sharp reality check, with the algos posting a net loss of $9,965.00 across just three trading days and 60 total trades. Despite generating $10,723.75 in gross profit, losses of $20,688.75 overwhelmed the upside, yielding a 41.7% win rate and a profit factor of 0.52. The cumulative account P&L stands at $201,980.94, still solidly positive year-to-date, but this week's drawdown reinforces the volatility regime we're operating in. Tuesday the 13th was the softer session, closing at minus $225, while Wednesday the 14th proved brutal, bleeding $8,412.50 alone.
The high-volatility regime confirmed by our AI Regime filter at 100.0% confidence created exactly the conditions where technical entry buckets degrade. Both active simulations are now flagging the same structural issue: clustering of weak entry times. The ES simulation suggests a daily loss limit of approximately $1,715, while the NQ edge is recommending $1,230, both grounded in drawdown history and loss distribution patterns. Blocking the consistently underwater time buckets—08:30, 13:00, and 10:10 on the ES side—could reduce whipsaw exposure without sacrificing edge during cleaner volatility windows.
The AI Sentiment reading is negative and AI Pi sits at 52.6%, suggesting regime uncertainty at near-equilibrium levels. However, seasonality data for this juncture in midterm election years points constructively forward: the next trading week has historically averaged +1.08% with a 74% win rate across nineteen comparable periods. That statistical setup, combined with a likely regime transition as volatility compression sets in, suggests the algos should be positioned to re-engage on stronger technical confirmation rather than forced entry during choppy overlap sessions.