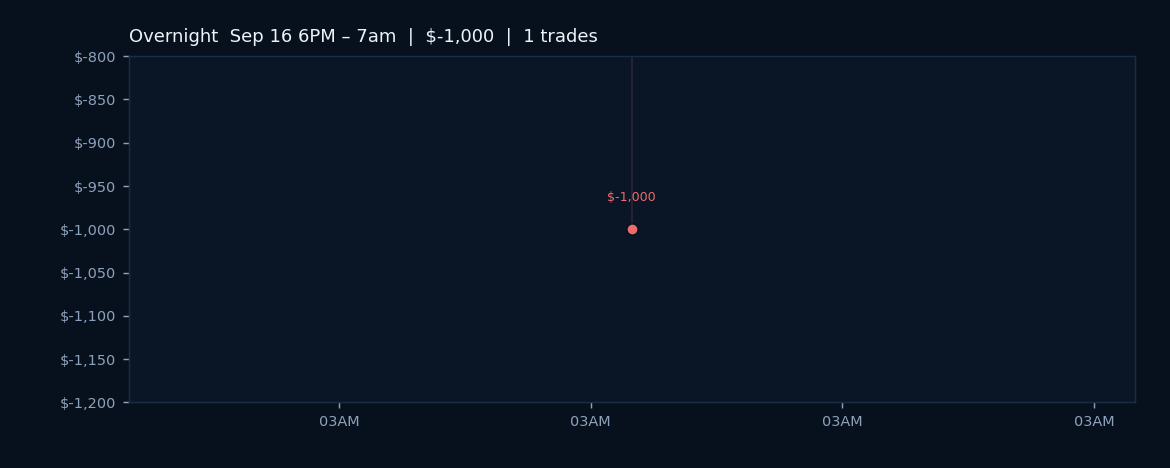
Overnight trading in ES and MES produced a net loss of $2,000.00 with a 0.0% win rate, setting a cautious tone ahead of the cash open. Geopolitical risk has surfaced as a tangible headwind after Israeli Prime Minister Netanyahu declared intentions to topple the Iranian regime, injecting fresh uncertainty into energy markets and risk positioning. Simultaneously, the Bank of England delivered hawkish signals this morning, with Governor Bailey indicating that monetary policy may need to tighten further if Middle East conflict persists and second-round inflation effects emerge, while traders are now pricing only 38bps of rate hikes through year-end (down from prior expectations). The ECB's Rehn countered with a more dovish posture, noting that inflation dynamics have shifted since earlier assessments, but the divergence between central banks underscores fragmentation in the global policy outlook.
The AI Sentiment reading stands at negative, and the AI Pi sits at 59.8%, reflecting hesitation across systematic measures. Our regime filter locks in low_vol with 100.0% confidence, meaning volatility expectations remain compressed despite headline risks. This technical posture creates a particular tension: geopolitical shocks and policy divergence typically spark vol expansion, yet the regime system sees none incoming. Seasonality data from midterm years (n=19) shows a -0.60% average return in the week ahead with a 47% win rate, trailing the all-history baseline of +0.18%, painting a mixed historical picture for this juncture in September.
We carry one open position into the session: SimES813RSISTNS holds a short contract in ES at 7678.75 (now showing $400 unrealized loss at 7670.75). The technical rules that govern this trade remain unaltered by overnight headlines or central bank commentary; the RSI filter and ATM stop/target template will execute their programmed logic independent of geopolitical developments or policy shifts. No fresh AI recommendations have issued this morning, and with no high-impact U.S. economic data on the docket over the next 48 hours, the session will likely hinge on risk sentiment and positioning adjustments in response to international events rather than domestic data.