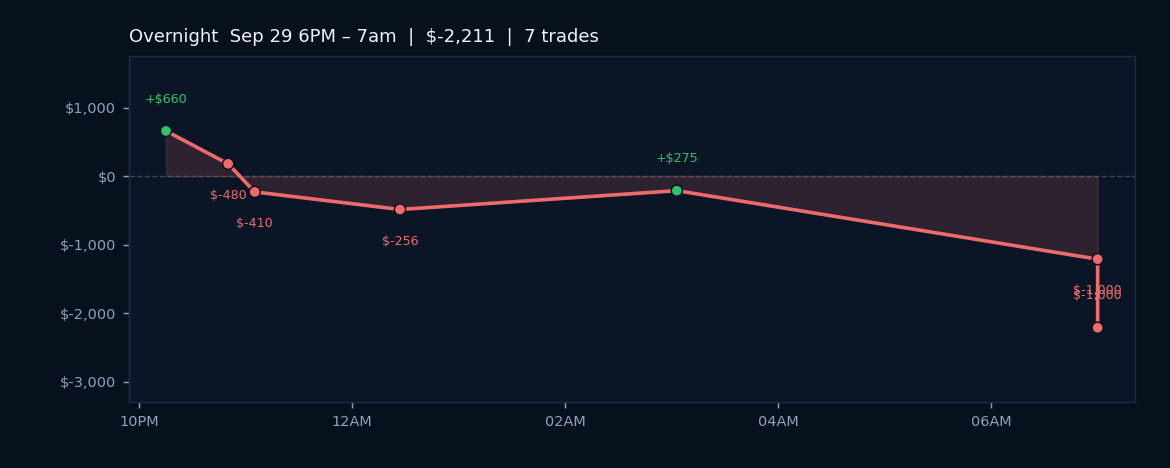
Overnight trading delivered a $-2,211.25 drawdown across seven contract scalps in ES and NQ, posting a 28.6% win rate as pre-market chop intensified ahead of this morning's economic calendar. The overnight session reflects broader volatility in equity index futures as market participants digest a sharp deterioration in housing demand: MBA mortgage applications dropped 6% overnight while the 30-year mortgage rate spiked to 7.30% from 7.12%, the steepest weekly climb in recent months. This cooling in housing demand arrives against a backdrop of mixed central bank commentary from the Bank of England, where officials signaled resilience in UK household finances while flagging vulnerabilities in private credit markets and calling for leverage ratio reforms in early 2027.
Today's macro calendar brings two critical data points: the Core PCE Price Index month-over-month (forecast 0.3%, previous 0.2%) and Final GDP quarter-over-quarter (forecast 1.5%, previous 1.5%), both due this morning and likely to reset expectations around rate trajectory if inflation reaccelerates or growth disappoints. Apple's product launch announcement earlier this morning (Home Hub and updated Apple TV/HomePod Mini) lands with minimal immediate market-moving impact, though sentiment around consumer discretionary remains fragile given mortgage headwinds. The AI Sentiment reading stands positive with an AI Pi of 60.3%, yet the AI Regime filter shows "chop" at 100% confidence, signaling choppy, directionless price action heading into the open; seasonality for this point in midterm election years suggests a tailwind, with the S&P 500 averaging +1.51% over the next week historically.
One short crude contract (CL 11-26 short @ 89.29, unrealized loss $-1,290, last trade 88.0) remains open from yesterday's session. The regime filter's chop reading will govern today's execution under standard RSI filters and ATM stop/target templates with no adjustments for overnight news flow or mortgage data surprises.