Energy tensions escalate overnight as Saudi Arabia signals crude cuts to European refiners, sharpening the macro backdrop into Friday's session. ECB President Lagarde's messaging acknowledges energy as a significant variable while cautioning that rate moves depend on growth and consumption dynamics beyond commodity prices alone. JP Morgan's revised forecast now pencils in a 25 basis point hike in March 2027 after December, reversing prior expectations for a pause, suggesting the central bank will maintain restrictive bias longer than previously priced. Meanwhile, Italy's Economy Minister flags rising debt burdens at an alarming rate, creating policy divergence tension within the eurozone just as fiscal discipline targets (France targeting 3% deficits) come under strain from energy repricing.
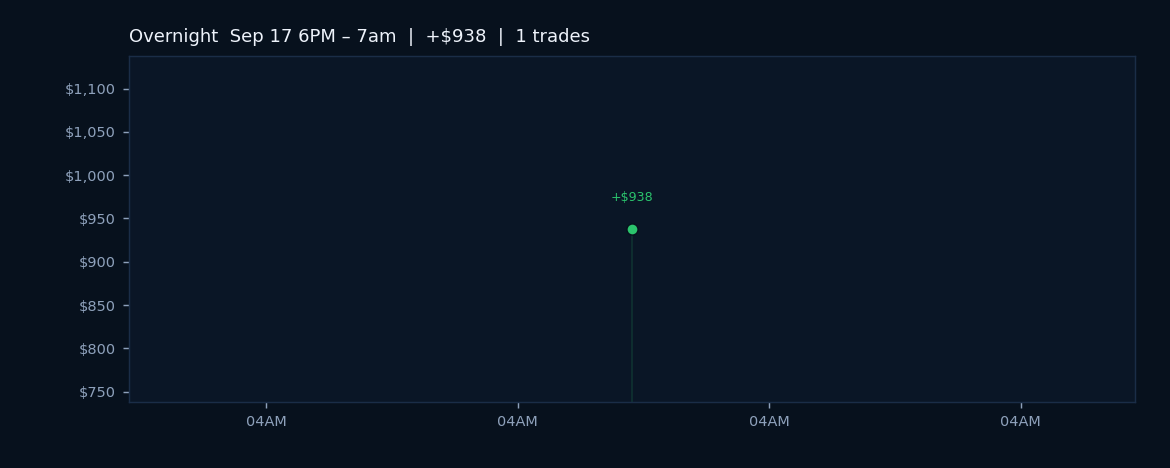
Overnight ES, M2K, MES, and MNQ activity yielded $108.25 net P&L on 12 trades with a 58.3% win rate, setting a productive tone into the European cash open. Two contracts carry into Friday: a short ES position at 7729.25 sitting with $812 unrealized gain on a last print of 7745.5, and a long MES cluster of 10 contracts at 7717.5 with minimal unrealized edge. The AI Sentiment reading flashes negative while Pi registers 52.2%, but the dominant signal is the AI Regime's high_vol classification at 100% confidence, indicating elevated volatility structure regardless of directional lean. Seasonality data from S&P 500 history through mid-term years shows the week ahead tends toward a modest -0.44% average return with 53% win rate (n=19 years), a mixed signal against the longer baseline of +0.18%.
No high-impact US economic data arrives in the next 48 hours, leaving overnight sentiment and European policy messaging as the primary drivers through the cash open. Current open positions scale the overnight directional edge with technical precision, while intraday execution will remain anchored to RSI filters and ATM stop/target templates that define the strategy ruleset independent of headline flow.