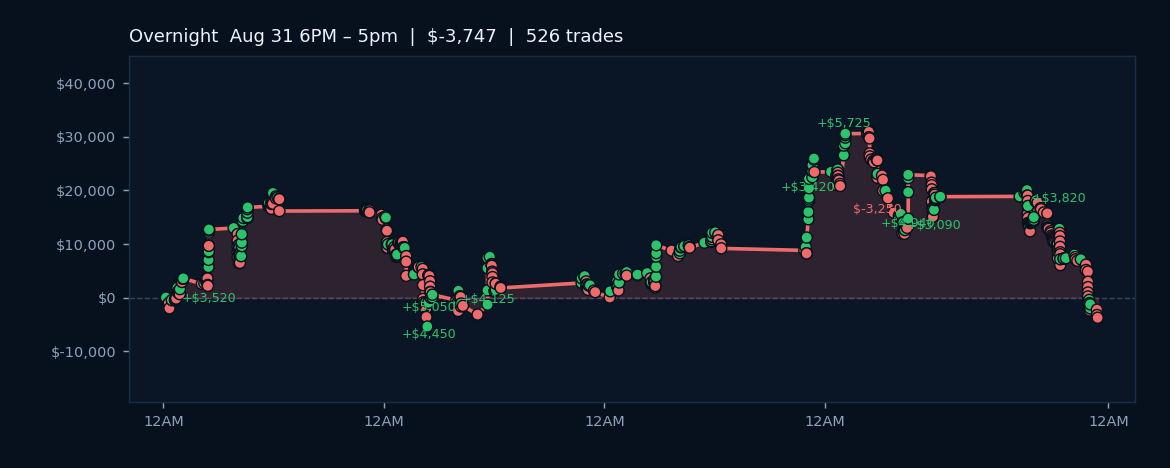
September 2026 closed with a net loss of $7,346.83 across 21 trading days and 494 total trades, delivering a 48.8% win rate that fell short of breakeven despite gross profits of $165,419.97. The spread between gross profit and gross loss ($172,766.80) underscores a month where position sizing and loss management became the defining challenge. A 0.96 profit factor reflects a familiar dynamic in high-volatility environments: winning trades generated solid returns, but losing trades punched harder. The best session, September 20th, captured $14,230.00 in gains, while September 7th's drawdown of $11,838.77 demonstrated the asymmetry that plagued the month.
The month unfolded under negative AI Sentiment and an AI Regime locked in high_vol with 96.7% confidence, a combination that typically widens bid-ask dynamics and amplifies stop-hunts on intraday swings. The AI Regime reading validates what the P&L distribution shows: volatility expanded but did not translate to directional clarity. Current active recommendations from the AI Labs OS flagged critical vulnerabilities, particularly around specific entry time buckets (08:30, 13:00, 10:10 showed consistent weakness) and a maximum daily drawdown of $12,175.00 that outpaced the suggested daily loss limit of $1,715.00 by a significant margin. This gap signals that position sizing protocols were not sufficiently restrictive relative to realized intraday volatility.
The cumulative P&L stands at $160,966.86 year-to-date, preserving net profitability despite September's headwind. However, the month's negative contribution marks a regression worth examining. Looking forward, the seasonality data for midterm-year periods shows a historical +1.51% average return over the next trading week with a 68% win rate (n=19 years), offering a contrarian note to the current negative sentiment regime. An AI Pi reading of 56.0% sits only marginally above neutral, suggesting limited directional conviction from the broader market structure. The combination of high volatility confirmation, weak entry-time clustering, and approaching macro events (Core PCE and Final GDP today) argues for tighter loss limits and continued adherence to the weakest-bucket blocking rules through the period ahead.