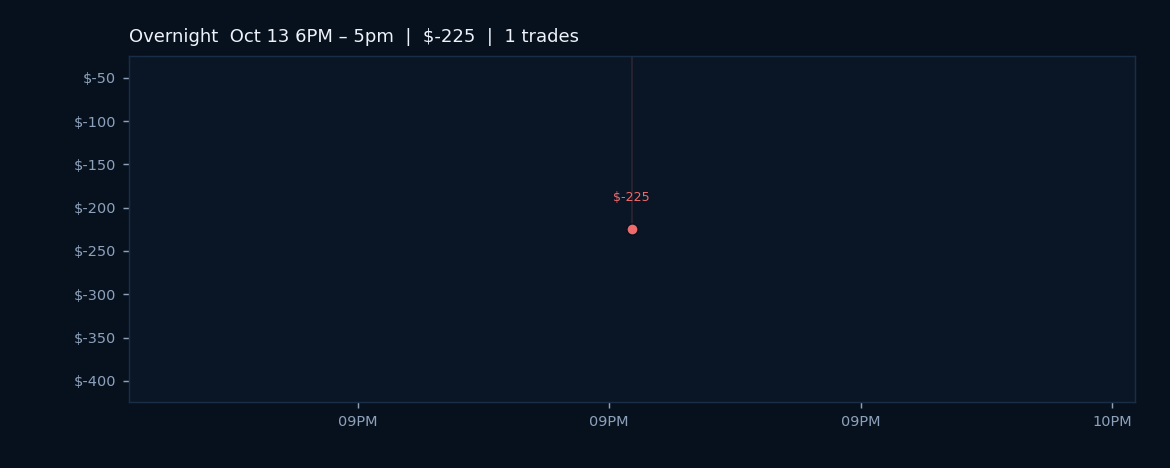
The session drew down -0.11% from prior equity, closing with a net loss of $225.00 against cumulative total P&L of $210,393.44. One trade was taken and lost, producing a 0.0% win rate with $0.00 in gross profit offset entirely by $225.00 in gross loss, yielding a profit factor of 0.0. The minor drawdown arrived as AI Sentiment turned negative and the Fed's Mary Daly reiterated a measured approach to further rate hikes, emphasizing no urgency despite persistent inflation concerns. Core CPI data released today came in at 0.2% m/m and 2.5% y/y, tracking close to forecast, while headline CPI printed 0.6% m/m and 3.6% y/y — providing no fresh shock to repricing expectations. Equity index futures held near prior-day close: ES opened within the prior session's range near 7834, while NQ and YM similarly consolidated overnight levels, reflecting the cautious tone that followed the inflation read.
The broader backdrop remains constructive for trend strategies, with AI Regime locked in trend mode at 100.0% confidence, yet AI Pi sits at 65.5% — above historical midline but below extreme conviction thresholds. Anthropic's Q3 revenue climb to $16.8 billion underscores continued capital deployment into AI infrastructure, though equity momentum remains fragile heading into a week when NFLX, META, and TSLA all report earnings. The platform's active AI recommendations flag enforcement of tighter daily loss limits (near $1,715 for the primary sim) and the blocking of historically weak entry buckets spanning the 08:30, 13:00, and 10:10 time windows, suggesting the algos are being systematically refined to avoid low-probability slots.
Seasonality data compounds caution: midterm-year trading weeks from this point average -0.33% with only a 37% win rate across 19 historical instances (n=1950-2026), marking a red seasonal tendency against the all-history baseline of +0.18%. Tomorrow's Core PPI m/m (forecast 0.3%) and retail sales prints will test whether disinflation narratives hold, while Fed Chairman Warsh speaks, potentially adding color to the rate trajectory. Trend confirmation remains intact, but the convergence of negative sentiment, seasonal headwinds, and upcoming macro volatility argues for strict adherence to loss-limit protocols and elevated trade selection rigor through the week ahead.