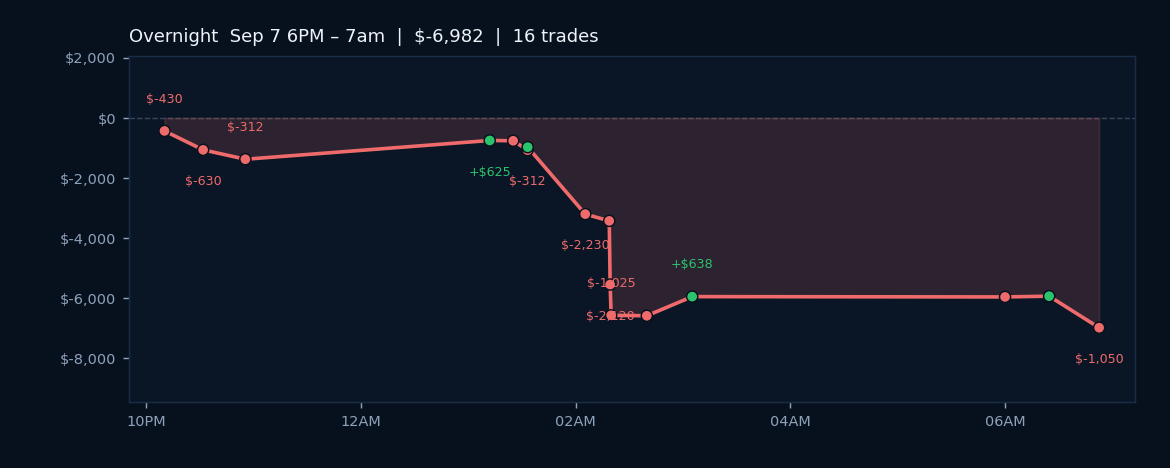
Overnight session delivered a $-6,877.50 loss across 18 trades with a 33.3% win rate, confined to ES, GC, MES, and NQ contracts as pre-market momentum failed to build conviction. This morning's data flow carries mixed signals: the US NFIB Business Optimism Index printed 98.7, missing consensus of 99.3 and retreating from the prior 99.80, suggesting small-business confidence has begun to soften despite Chancellor Healey's comments that the UK economy is "starting to turn a corner." Meanwhile, BNP Paribas has pushed its Bank of England rate-hike expectation from September to November 2026, reflecting persistent growth fragility abroad and cooling inflation momentum that may limit near-term upside for equity futures.
On the geopolitical and tech fronts, the Commerce Department's $100 million deal with D-Wave under the chips act underscores continued US investment in quantum computing infrastructure, a structural positive for NQ but offset by diplomatic noise around Iranian nuclear talks and US efforts to secure Venezuelan mineral access. These stories trade at the margin of broader macro sentiment rather than moving near-term index futures, yet they reinforce a risk-off undertone already present in overnight price action and reflected in this morning's negative AI Sentiment reading.
The AI Regime is locked in low_vol mode at 100.0% confidence, which typically constrains intraday swings and favors range-bound scalping strategies over directional conviction. Seasonality data from midterm-years shows the next week averages a -0.41% move with a 58% win rate, a mixed omen that aligns with today's caution. Four positions carry modest open P&L across the NQ and ES complex: a short NQ 09-26 contract up $710 and three ES positions near breakeven to slightly negative, all governed by fixed RSI filters and ATM stop/target templates with no discretionary rebalance warranted by this morning's macro backdrop. No fresh AI recommendations are in effect, and no high-impact US data releases loom in the next 48 hours.