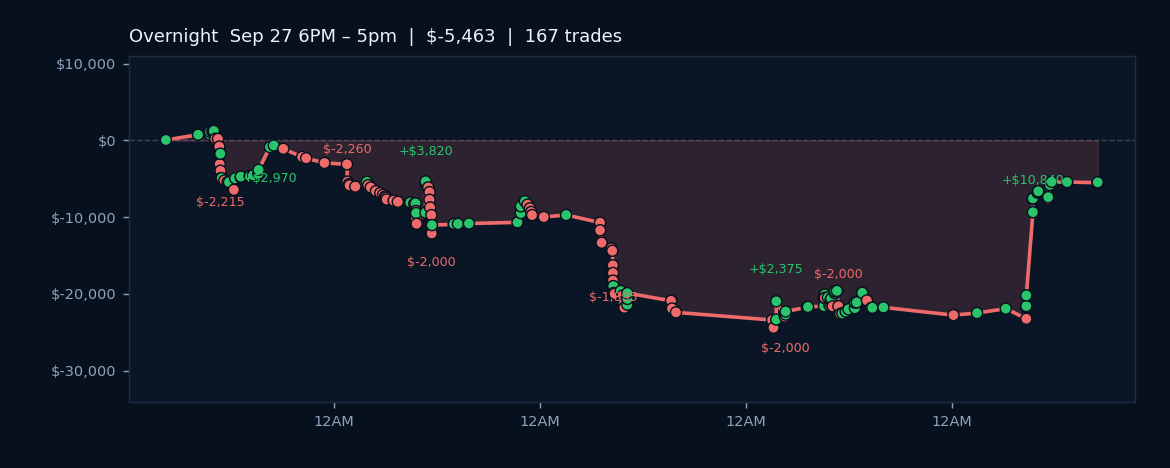
The week of September 28 through October 2 delivered a sobering lesson in execution discipline, posting a net loss of $4,796.66 across 134 trades and a 47.8% win rate that underperformed breakeven. Despite solid gross profit generation of $45,699.73, the accounts bled $50,496.39 in losses, yielding a profit factor of 0.91 and net negative performance that erased earlier week gains by Friday's close. The best session, Thursday October 1st, captured $16,302.09, yet Wednesday's $11,580.50 drawdown on the worst day proved the more consequential trade, illustrating the volatility asymmetry plaguing execution this period.
The high_vol regime confirmation at 100% confidence aligns precisely with this week's whipsaw character. Entry timing deteriorated markedly, with AI analysis flagging five distinct 5-minute buckets as chronic underperformers, with morning opens at 08:30 and 10:10 alongside midday 13:00 windows consistently generating negative PnL. The regime filter itself is functioning as designed, but entry selection within high-vol environments demands tighter discipline. Current AI recommendations have surfaced daily loss limits near $1,715 on the primary simulation, with maximum realized drawdown reaching $12,175, suggesting position sizing remains slightly generous relative to realized slippage in fast markets.
Seasonality data offers modest encouragement ahead. Historical S&P 500 performance from this calendar point in midterm election years (n=19 occurrences) has averaged +1.03% with a 63% win rate, materially outpacing the all-history baseline of +0.18%. Against this backdrop, the negative AI sentiment reading and AI Pi hovering at 52.5% suggest next week enters contested territory. The high_vol regime may persist through early October, necessitating stricter adherence to the flagged entry-bucket filters and daily loss guardrails before tactical loosening is warranted.